

Originally posted by RyderzUnlimited
View Post
-
What happens if your house burns down?
-
You say you already have enough education...yet...you are only making money irregularly...and staying "afloat"...
To me this say one of four things:
1. the education you have is useless for getting a higher paying job...so you need a different one.
2. you are not perusing a career with your current "degree" thus this degree is useless and you need a different one to get a higher paying job
3. this "education" is not really a college degree...which means you need a college degree...because you get higher paying jobs with higher degrees
4. your education is sufficient you are just gaining experience...meaning you are in an entry level position...thus your pay should significantly increase each and every year.
Fact is, you NEED a college degree to make good money and to get a higher paying career.
 facts of life suck, but you have to look at what is going on now...and right now...your current education is not getting you what you need. Staying "afloat" is not living...it sucks...I know...I am there now. Once I finish school no more floating...I will be flying. Income will triple once I finish school.
My advice...use the money to get you through school...irregular jobs will help with paying for school/bills as will the cash help as you cut back some on those things.
Work smarter not harder...
I have family member that is a nurse and makes 70k a year working 40-48hrs a week...3-4 days a week...sometimes 5 a week.
Another family member making the same amount, with no degree (70k)...BUT he works 6-7 days a week..70hrs a week...EVERY...week.
Which is better?
Obviously I do not know your full situation...so take my advice with a grain of salt...only you know what is best for you.
happens more than folks realize...mostly to older folks...had a friend who granny did this...lost 100k in a house fire. Your home insurance (IF you have it) will not replace that.Originally posted by ChIoVnIdCa View Post
plus even those crappy bank savings accounts are better than your mattress ...you get SOME return...and insuranceLast edited by bcjammerx; 09-26-2010, 05:24 AM.__ __
Comment
-
bcjammerx, I completely agree with everything that you said. And I do take most everything people say with a grain of salt, especially on internet forums... never know what sort of nut job is on the other side . And I purposely left a lot of shit out as I am not one to post personal information about me all over the internet, so you and everyone else obviously couldn't have a complete understanding of the situation.
Yes I do work irregularly, but that is also a lot a to do with my choice. Why? I have always been the type to work by myself/as my own boss and it works better that way (for me at least ). Sixteen years ago it was maintaining lawns by my little ol self. After that it was making mobile audio installation products (spacers, baffles, rings, fiberglass molds, boxes, etc.). And now I've moved onto other things, including freelanced graphic design for several different companies and individuals.
I have also built my own little workshop for my business that I am trying to get going (all of which is completely 100% paid for, no debt).
And without my education I would be nowhere even close to where I am today. I live in Idaho where we rank 49th in the nation for sending high schoolers to college and 43rd for graduating them, so I have seen and still continue to see the struggles of those who choose not to get any further education. Work smarter, not harder is a HUGE understatement here.
So by staying afloat what I am really doing is not putting myself in debt up to my eyeballs, able to put some $$$ away into savings, and splurge on the occasional toy.
Thank you for the input, I appreciate that you took the time write that. Maybe someone will read that and really take it to heart.
As for the investments side of this thread, everything will be squared away as planned (large portion into a long term investment/account, a little less into a shorter higher risk situation, and the remainder will stay liquid in a very low interest bearing account).Comment
-
That is most definitely NOT a fact. I'm not even 21, I have a high school degree, and relatively little work experience (just real experienceOriginally posted by bcjammerx View Post ), yet I'm making 70k/yr working at Dell. NO degree. I also don't work 70 hours a week. In fact, I rarely go over 40.
There is this strange myth that says you "must have a degree to make any real money" and it is just plain false.
I will not say, however, that getting a degree is a bad idea. It's a great idea, and I highly recommend it. It just bothers me when someone says you "HAVE to have a degree to do anything worthwhile!"Last edited by foamypirate; 09-26-2010, 12:14 PM.Originally posted by sweet91accordComment
-
The problem with saying "It doesn't take a college degree to get paid well" is that most people read it as "You don't have to work hard to get paid well" the amount of work most people put into high school is laughable.
I'm not saying that it isn't possible to do well without a college degree, but, numbers-wise, getting a college degree is the best investment you can make. The average college graduate will make over $1,000,000 more than an average high school graduate over his lifetime.
As to your choice for investments, you sound like you've done a pretty good job. The real key to saving is to save early and often. Putting in a lot now is great, but putting in a decent amount every year is how you really build a solid savings plan. If you are putting away $5,000 a year now and living fine try and bump that up to $6,000 next year. This guy has a bunch of great tips to saving. He's a little short sighted on some issues, but the bulk of his ideas are great to new investors.
http://www.iwillteachyoutoberich.com...or-psychology/
Don't play the market, you will loose terribly.
Originally posted by Maple50175Comment
-
-
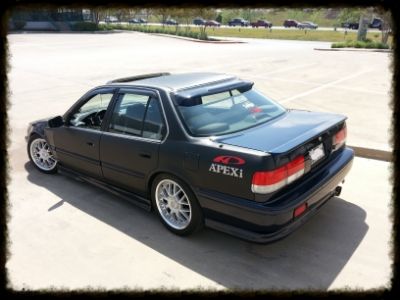
buy a supra!!! thats what i would do. just kidding. seriously id put it in an ira and 401k and put a little in stock towards pharmicuticals,you never know. i too recently came across a huge amount of money as well.i paid off my debts and im still considering what to do with the rest. i admit i spent a little bit for myself to have fun and uprade my ride a bit but, not much. its good that at least your thinking straight. theres some people who would blow it all without even realizing that theres still the future to worry about and that theres far more important things than a car! good luck with everything!
Comment
-
Almost everyone who tries to "beat the market" end up getting beat by the market.Originally posted by HondaB18 View Post
If you put your money in a 401(k), make sure the funds are managed by competent fiduciaries who are paid based off of fees and not commissions. Also make sure the funds are diversified properly according to the current market conditions. I'm in the retirement planning industry so I can't tell you what's appropriate for the current market, or won't unless you're a client. My Member's Ride Thread
Bisimoto header before & after dyno
1993 10th Anniversary: F22a6, H23IM, Bisimoto header, Custom mandrel exhaust, 5spd swap.Comment
-
Agreed, diversification is key to any good savings plan.
Originally posted by Maple50175Comment
-
^^ Also something most people don't understand. A 401(k) is not designed or supposed to be an investment. It is a savings account that will hopefully beat inflation and will be available to you at retirement as secure income. You should never expect to make huge gains through any retirement vehicle. There are better vehicles to make real investments in for gains and they come with greater risk.Originally posted by Tnwagn View PostMy Member's Ride Thread
Bisimoto header before & after dyno
1993 10th Anniversary: F22a6, H23IM, Bisimoto header, Custom mandrel exhaust, 5spd swap.Comment
-
-
Then what is a 401k suppose to be...? Anything with gain/loss is an investment. Are you confusing investments with securities? You are in the retirement planning industry (reading back, you don't want to diversity and invest in the current market conditions, any investor will tell you to look into the future). What most people don't understand is their 401k and how to invest so they put their money on autopilot hence the investment vehicle options.Originally posted by 19dabeast85 View Post
What company do you work for?Comment
-
The 401(k) vehicle, which is governed mainly by the ERISA (Employee Retirement Income Security Act) regulation, is designed for retirement income security. The reason why you THINK it's an investment is because it has been advertised as that. Because way too many people treated their 401(k) as an investment instead of a savings account, they were holding way too high of a percentage of equities and subsequently lost 35-50% of their portfolio value in the last 2 years on average.Originally posted by HondaB18 View Post
I never said not to diversify, I actually said pick a fiduciary who PROPERLY diversifies the portfolio based on current market conditions. I also never said not to invest in the current market, I said I will not share HOW and WHAT to invest in in the current market unless you're a client.
A 401(k) uses investments(securities and bonds mainly) to maintain and slightly build portfolio value, hopefully enough to outrun inflation and return small gains on top of that. In the current market, if your 401(k) is aimed at anything over 8% growth then it is invested too riskily.
Because the 401(k) is designed (supposed to be but most managers don't) to be a retirement income security vehicle with low gains, you must properly fund it. You will need to put 15-20% of your income in your 401(k) to be able to retire and draw your current income till death. If you are being promised full retirement while funding less than 15% of your income to it then your plan manager is using assumptions and/or investments that are too risky and not considered prudent under ERISA regulation.
Managers have gotten away with investing participants money much more risky than is considered prudent for way too long because the regulations have not been enforced. The managers aren't held responsible for the plan value so they invest however they want essentially.
BTW, most target date funds are WAY too risky, most of them still having a 60% equity ratio AFTER retirement. Every employee MUST do their research before enrolling in their employer's plan or any other for that matter. Here's a tip, if you find out your 401(k) is managed by an insurance company then find another 401(k) to participate in. Insurance companies usually (read 95% of the time) have very high internal expenses that are not disclosed and are pulled out of asset gains. Your report you receive from them will show a gain, but that gain would have been 1-2.5% higher with a prudent retirement plan manager. Just because they have a license to sell insurance does not mean they know anything about choosing the correct investment strategy for an employer.My Member's Ride Thread
Bisimoto header before & after dyno
1993 10th Anniversary: F22a6, H23IM, Bisimoto header, Custom mandrel exhaust, 5spd swap.Comment
-
I see what you're getting at. But no thanks to being a client. I only use my company sponsored 401k for the price matching, I use my ROTH IRA for my own decision making as well as my own personal account. We'll see how things go in a few months.Originally posted by 19dabeast85 View PostComment
-
My clients are companies, we audit 401(k) plans for non-disclosed fees and non-prudent investment decisions and recommend changes to benefit the employees, individuals can't be my "clients".Originally posted by HondaB18 View Post
I will recommend this though: Drop the ROTH unless you're fully contributing to your traditional plan. Here's why.
You can contribute to your regular plan and receive the tax credits now saving you a ton of tax dollars. At retirement you can then roll it over into a lifetime annuity that pays you annually. This annual income is "taxable" but you likely will not be withdrawing more than $40k annually (times cost of living now to then). After your standard tax deduction and exemption you get to use each year after retirement you'll be paying a VERY low income tax on that money (more than likely 5-10%).
If you contribute to a ROTH right now, you pay tax on that money right now at your marginal tax bracket which may be 15% or more.
The above rule remains true for anybody regardless of current income level until your traditional 401(k) plan reaches assets of ~$450k. At that point you will CONSIDER a ROTH.
If you just downright have to have a ROTH then you should have one, every individual has different reasons for wanting specific vehicles, BUT it doesn't make the most sense financially.My Member's Ride Thread
Bisimoto header before & after dyno
1993 10th Anniversary: F22a6, H23IM, Bisimoto header, Custom mandrel exhaust, 5spd swap.Comment
Comment